

Roofing King
Expert Roofing Tips & Insights to Protect Your Home
RECENT ARTICLES
How to Handle Insurance Claims for Roof Replacement in Lakeland
Dealing with a damaged roof is stressful enough without the added headache of figuring out the insurance claim process. If you’re a homeowner in Lakeland, FL, and you suspect you need a roof replacement, understanding how to navigate your insurance claim can make things a lot smoother. Let’s walk through the key questions homeowners have about handling insurance claims for roof replacements.
How Do I Know If My Roof Damage Qualifies for an Insurance Claim?
Not every type of roof damage is covered by insurance. Generally, policies cover sudden or accidental damage, like from a windstorm, hail, or fallen tree. Age-related wear or lack of maintenance usually isn’t covered. The first step is to review your homeowner’s insurance policy and see what types of roof damage are included. If you’re not sure, call your insurance agent. It's also wise to document the damage as soon as you notice it—take clear photos and note the date and any details about the event that caused the damage.
What Should I Do Immediately After Discovering Roof Damage?
Safety comes first. If your roof is leaking or parts are missing, try to prevent further interior damage by placing buckets or tarps inside until repairs can be made. Next, document everything—take photos of the inside and outside damage, and keep notes about when and how you discovered the issue. Then, contact your insurance company to report the damage and start the claims process. Most insurers have a timeframe for filing a claim, so try not to delay. It’s also a good idea to reach out to a local roofer, like Roofing King, to get a professional assessment of the damage. Some roofers can help you with documentation and even meet with the adjuster during the inspection.
What Happens During the Insurance Inspection?
Once your claim is filed, the insurance company will send out an adjuster to inspect your roof. Their job is to determine the cause and extent of the damage and estimate the cost to repair or replace the roof. It helps to have your own roofer present during this inspection. Roofers know what to look for and can point out issues the adjuster might miss, especially with types of roofing common around Lakeland like shingle, metal, or tile. After the inspection, the adjuster will submit their report, and you’ll get a decision from the insurance company about what repairs or replacement they’ll cover.
How Do I Choose the Right Roofing Materials for My Claim?
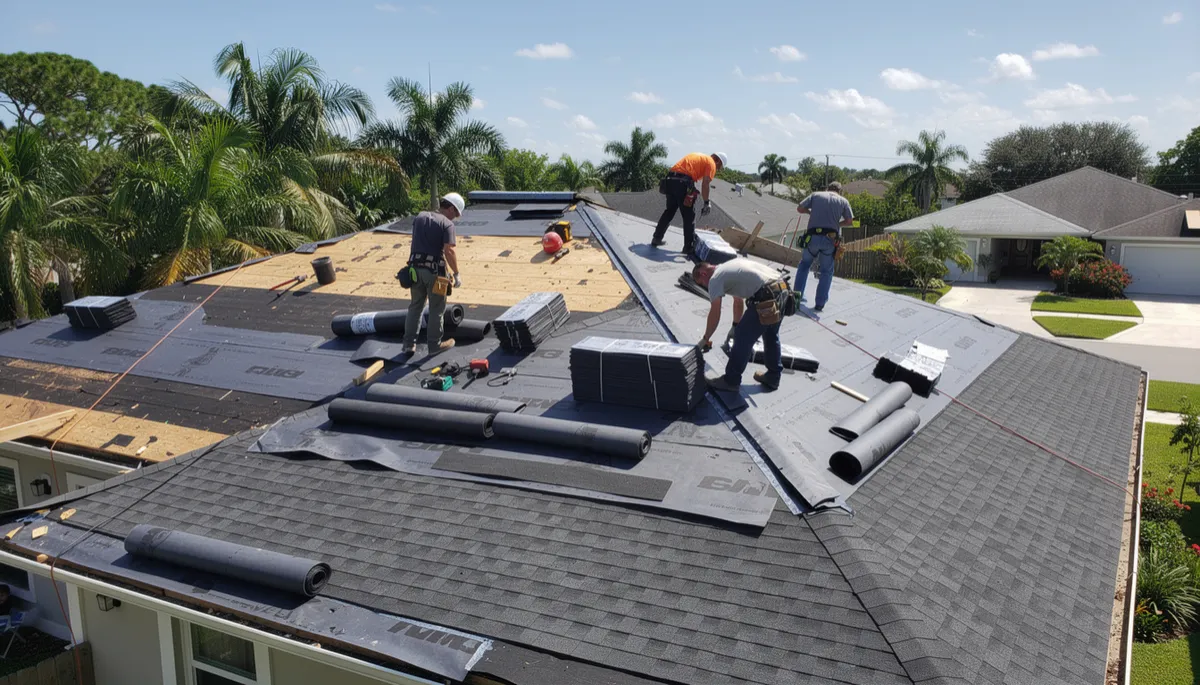
If your insurance claim is approved for a full or partial roof replacement, you’ll usually get an estimate based on the type of roof you already have. However, this is a good time to consider your options. Asphalt shingles are common and affordable, but metal and tile roofs are popular in Florida for their durability and weather resistance. Peel and stick underlayments and TPO roofing are also options for certain types of homes or businesses. Talk with your roofer about what materials make sense for your home, your budget, and your insurance payout. Sometimes you can upgrade materials by paying the difference out of pocket.
What Are Common Pitfalls to Avoid During the Claims Process?
Insurance claims can get tricky, especially if there are disagreements about the cause of the damage or the cost of repairs. Here are a few things to watch out for:
- Not documenting enough: Take plenty of photos and keep records of all correspondence with your insurer.
- Agreeing to the first settlement: Sometimes initial offers are low. Review the adjuster’s report carefully and compare it to your roofer’s assessment.
- Hiring unlicensed contractors: Always work with a reputable local roofer who knows the insurance process and local building codes.
- Ignoring deadlines: Insurance companies have strict timelines for filing claims and submitting paperwork. Missing these can jeopardize your claim.
How Long Does It Take to Get My Roof Replaced Through Insurance?
The timeline can vary. After the inspection, it can take anywhere from a few days to a few weeks to get your claim approved. Once you have approval, your roofer can usually start work within a week or two, depending on weather and material availability. In Florida, especially during storm season, schedules can fill up quickly, so it pays to get the process started as soon as you suspect damage.
Frequently Asked Questions
Will filing a claim make my insurance rates go up?
Not always. Rate increases depend on the cause of the damage and your insurer’s policy. Widespread storm damage claims often don’t lead to individual premium increases, but claims related to maintenance issues or repeated claims might.
What if my insurance company only approves a partial replacement?
If your adjuster only approves repairs or a partial replacement but your roofer believes a full replacement is needed, ask for a re-inspection. You can provide additional documentation or get a second opinion from another roofing professional to support your case.
Can I choose my own roofing contractor?
Yes. You aren’t required to use the contractor your insurance company suggests. It’s your right to choose a reputable local roofer who understands the particular roofing needs and weather challenges in Lakeland.
What is a deductible and how does it affect my claim?
Your deductible is the amount you pay out of pocket before your insurance coverage kicks in. Make sure you know your deductible amount and be prepared to pay it directly to your roofer once work begins.
If you’re facing a roof replacement and need help navigating your insurance claim, Roofing King is here to help. We’ve helped many Lakeland homeowners work through the process step by step, so you can get your roof back in shape without unnecessary stress. Reach out anytime to discuss your situation or set up a roof inspection.

Google Reviews


What Sets Us Apart
At Roofing King, we are proud to be the trusted choice for residential and commercial roofing. Our commitment to integrity and quality shines through in every project, ensuring our clients receive the royal treatment they deserve.
Roofing King puts customers at the heart of everything we do. We know that your satisfaction is the key to our success. That's why we go the extra mile to ensure you are thrilled with our services, from start to finish.
Our expert and certified installers at Roofing King bring years of experience and skill to every project. With their dedication to excellence, you can trust that your roof will be installed with precision and care.
At Roofing King, we only work with the finest roofing materials on the market. Combining our expertise with top-tier products ensures your roof not only looks stunning but is built to last for years to come.
🔒 We value your privacy. Your data is encrypted and we will never share it with third parties.
GET STARTED NOW (863) 670-8517

GET A QUOTE
OPENING HOURS
Monday to Sunday: 6:00 am to 6:00 pm
© Copyright 2026 Roofing King. All Rights Reserved. - Privacy Policy - Terms & Conditions - DMCA
Website built by ClientSwing